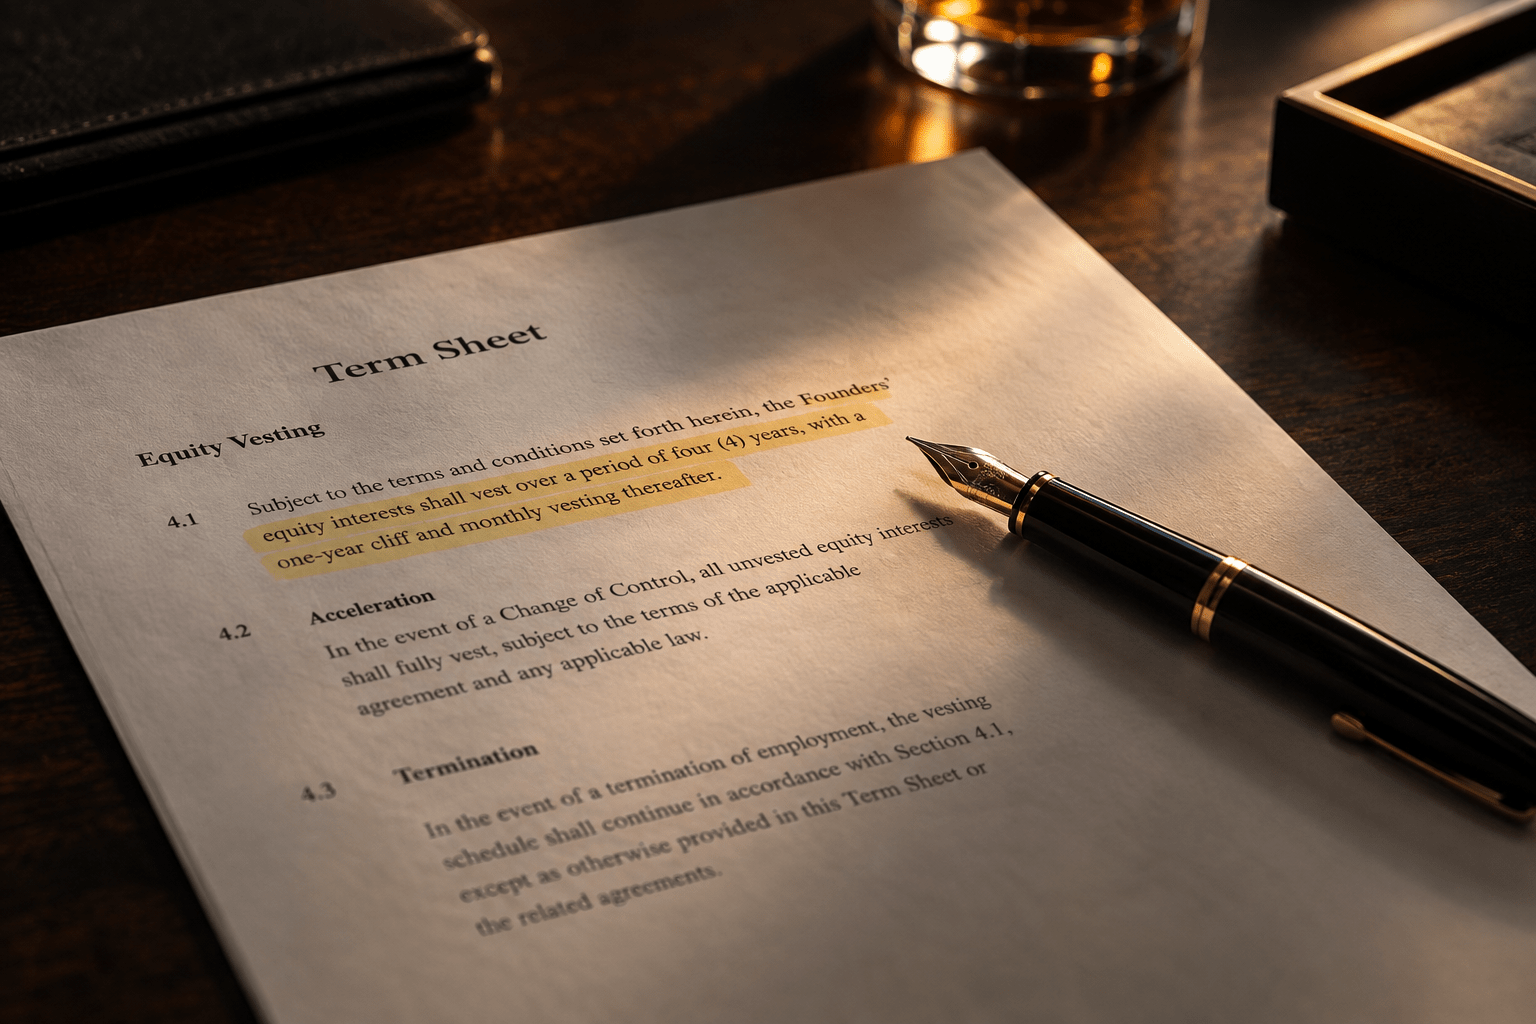
What placed CFOs remember about their first CFO negotiation is rarely the base salary number. It’s the clause on page four about what happens to unvested equity if the company sells. Most candidates don’t read that clause closely until someone points it out to them, and by then the offer is usually already signed. Knowing how to negotiate CFO total compensation (not just the salary line) is what separates a good outcome from a mediocre one.
What placed CFOs tell us, almost without exception, is that they spent more time negotiating base than any other component and got the least out of it. Equity, incentive structure, and severance terms moved the actual outcome. Base salary is the easiest number to benchmark and the hardest one to move, because it’s usually already set by a compensation study the board has seen.
The Expectation: Base Salary Is Where the Negotiation Happens
Candidates who’ve spent their careers on the corporate side come in with a corporate mental model. Base salary reflects seniority. A strong counter gets you 5 to 10 percent more. That’s how it worked at the VP and Controller level, and it’s reasonable to assume the CFO offer will follow the same pattern.
The reality in PE-backed companies is different. Base is often anchored to a market comp report the board or sponsor has already reviewed, the same process we walk sponsors through when they structure a CFO compensation package before a search even opens, and the range is tighter than candidates expect. Pushing hard on base can read as a candidate who doesn’t understand PE compensation structure, which is not the impression anyone wants to make before the deal closes.
The Reality: Where CFO Total Compensation Negotiations Actually Happen
Finance leaders we’ve worked with describe the real negotiation happening in three places: the equity grant, the incentive plan, and the terms around what happens if the company sells or the role ends early. Each one carries more long-term value than a base salary increase, and each one is negotiable in ways base often isn’t.
Equity is the biggest variable. What placed CFOs tell us is that the headline percentage matters less than the mechanics behind it. Vesting schedule, whether there’s a cliff, what happens to unvested shares on a sale, and whether the grant is time-based or performance-based all change what that equity is actually worth. The differences between stock options, RSUs, and phantom equity that we break down in detail here are exactly what candidates need to understand before they sit down at the table. A 1.5 percent grant with clean vesting and acceleration on exit can be worth more than a 2.5 percent grant with a four-year cliff and no protection.
The incentive plan is the second lever. Bonus targets tied to EBITDA growth or a specific exit multiple sound straightforward until a candidate asks how the target was set and who controls the calculation. When we ask placed CFOs what they wish they’d pushed harder on, the answer is usually the definition of the bonus metric, not the size of the bonus itself.
Severance and protection terms are the piece candidates negotiate least and regret most. A CFO role in a PE-backed company carries real execution risk. Sponsors change direction, portfolio companies get sold faster than planned, and a CFO can be let go through no fault of their own. Severance terms, and what happens to unvested equity if that happens, deserve the same attention as the salary line.
We ask placed CFOs what they’d negotiate differently. Almost none of them say base salary. Almost all of them say the vesting schedule.
Negotiate the Order, Not Just the Number
The CFOs we place who negotiated well didn’t necessarily negotiate harder. They negotiated in a different order. They treated base salary as a baseline to confirm, not a number to fight over, and spent their leverage on the equity mechanics and downside protection instead.
That requires understanding the structure before the offer arrives, not after. Finance leaders who ask a recruiter or a placed CFO to walk them through a typical PE equity grant before they’re in a live negotiation show up to that conversation with better questions and less anxiety about which battles to pick. It’s also worth asking how the back-end is structured on a second or third deal; we’ve argued elsewhere that equity participation should scale with proven exits rather than resetting to a flat number every time, and that’s a legitimate thing to raise if you’ve been through the cycle before.
It also requires being direct about which specific term matters and why, instead of pushing generally for more. Asking specifically about acceleration terms if the company is acquired within the first two years gets a clearer answer than asking for a bigger number. Precision reads as experience.
A Generous-Looking Number Can Still Be a Bad Deal
The most common mistake finance leaders describe is not asking about the equity mechanics at all, because the headline percentage sounded reasonable and the rest felt like fine print. The second most common mistake is treating the negotiation as adversarial, when a competent counterparty, a search firm managing the placement, is often willing to walk a candidate through what’s typical and what’s negotiable.
One placed CFO described accepting a role with a 2 percent equity grant that sounded generous, only to learn eighteen months later that a full four-year cliff meant leaving before year one would forfeit everything. The number had been right. The structure hadn’t been examined. That’s not a rare story. It’s close to the median one.
Most finance leaders moving into their first CFO role are negotiating equity and incentive structure for the first time, at exactly the moment they have the least standing to ask basic questions without feeling exposed. That discomfort is real, and it doesn’t fully go away. Knowing which questions to ask does.
Have something to share with our community?
Final Thought: The Negotiation That Matters Isn’t the One You Expect
The gap between what candidates think they’re negotiating and what actually determines their outcome is wide. Base salary feels like the negotiation because it’s the number everyone tracks. Equity structure, incentive definitions, and severance protection are where the real value sits, and they’re negotiable in ways base rarely is.
The CFOs we place consistently say the difference between a good outcome and a mediocre one came down to which questions they asked before signing, not how hard they pushed on the base number. If you’re heading into a CFO negotiation for the first time, it’s worth having someone in your corner who’s seen the structure of these offers before you’re the one reading the term sheet.